Showing posts with label GSTR-1. Show all posts

Wednesday, 22 January 2020

GSTR-3B Returns in a Staggered Manner

Ministry of Finance
Now the GST Taxpayers can file their GSTR-3B Returns in a Staggered Manner
                     #GSTUpdates #GSTR3B #DueDates #STAGGERED

Posted On: 22 JAN 2020 6:29PM by PIB Delhi
Considering the difficulties faced by trade and industry in filing of returns, the government has decided to introduce several measures to ease the process. The Finance Ministry today said that now GST taxpayers can file their GSTR-3B returns in a staggered manner.

Presently the last date of filing GSTR-3B returns for every taxpayer is 20th of every month. From now on, the last date for filing of GSTR-3B for the taxpayers having annual turnover of Rs 5 crore and above in the previous financial year would be 20th of the month. Thus, around 8 lakh regular taxpayers would have the last date of GSTR-3B filing as 20th of every month without late fees.

The taxpayers having annual turnover below Rs 5 crore in previous financial year will be divided further in two categories. The tax filers from 15 States/ UTs, i.e., Chhattisgarh, Madhya Pradesh, Gujarat, Daman and Diu, Dadra and Nagar Haveli, Maharashtra, Karnataka, Goa, Lakshadweep, Kerala, Tamil Nadu, Puducherry, Andaman and Nicobar Islands, Telangana and Andhra Pradesh will now be having the last date of filing GSTR-3B returns as 22nd of the month without late fees. This category would have around 49 lakh GSTR-3B filers who would now have 22nd of every month as their last date for filing GSTR-3B returns.

For the remaining 46 lakh taxpayers from the 22 States/UTs of Jammu and Kashmir, Laddakh, Himachal Pradesh, Punjab, Chandigarh, Uttarakhand, Haryana, Delhi, Rajasthan, Uttar Pradesh, Bihar, Sikkim, Arunachal Pradesh, Nagaland, Manipur, Mizoram, Tripura, Meghalaya, Assam, West Bengal, Jharkhand and Odisha having annual turnover below Rs 5 crore in previous financial year will now be having last date of filing the GSTR-3B as 24th  of the month without late fees.

The Finance Ministry said that the necessary notification in this regard would be issued later by the competent authority.

In a statement issues, the Ministry further said that it has also taken a note of difficulties and concerns expressed by the taxpayers regarding filing of GSTR-3B and other returns. The matter has been discussed by the GSTN with Infosys, the Managed Service Provider, which has come out with above solution to de-stress the process as a temporary but immediate measure. For further improving the performance of GSTN filing portal on permanent basis, several technological measures are being worked out with Infosys and will be in place by April 2020.


Need any assistance than 


Saturday, 21 September 2019

37th GST Council Meeting – Key Highlights

1. Policy Changes
New Return Filing System
New Return filing to be now introduced from April 2020 (Earlier proposed from Oct, 19)
New return system now to be introduced from April, 2020 (earlier proposed from October, 2019), in order to give ample opportunity to taxpayers as well as the system to adapt and accordingly specifying the due date for furnishing of return in FORM GSTR-3B and details of outward supplies in FORM GSTR-1 for the period October, 2019 -March, 2020.

Annual Returns and GST Audits
1) Gst Annual Return GSTR-9 and 9A  Optional for those with turnover upto 2 Cr for FY 17-18 & 18-19.
2) GSTR-9 is mandatory for those turnover is above 2 Cr.
3) No relief in case of GSTR-9C – GST Audit Form.
4) GSTR-9 & 9C to be made “Saral”.
Circulars (Old/New) to be issued on following matters

1) Refund RFD – 01A,       
2) Supply of ITeS
3) Rescinding circulars wrt Post-Sales Discounts
Issuance of circulars for uniformity in application of law across all jurisdictions:
a. procedure to claim refund in FORM GST RFD-01A subsequent to favourable order in appeal or any other forum;
b. eligibility to file a refund application in FORM GST RFD-01A for a period and category under which a NIL refund application has already been filed; and
c. clarification regarding supply of Information Technology enabled Services (ITeS services) (in supersession of Circular No. 107/26/2019-GST dated 18.07.2019) being made on own account or as intermediary.

2. Reduction in Rates and Rationalisation of various measures
Hospitality and Tourism Industry:
1) Tariffs 7500 & above – GST 18%,
2) Tariffs between 1,000-7500 – GST 12%,
3) Tariffs below 1000 – Nil,
4) Outside Catering – GST 5% without ITC (Reduce from 18%),
Job Work Sector
1) Diamond Job work – GST 1.5% (Reduce From 5% ),
2) Other Job-work – GST 12% (Reduce from 18%).
Warehousing
Exempted Storage & warehousing services wrt certain agricultural products 
Transportation
Export freight exemption further extended till 30th September, 2020
Insurance Sector
Exemption given to BSB Crop insurance of WB state & Life insurance services by Central Armed Paramilitary Forces 
Export Promotion
1) Exemption given to intermediary services where both supplier and recipient is outside India,
2) Place of supply for specified R&D Services and supply of chip design R&D Services shall be th to the location of service recipient
New Law for 2 union territory
Suitable amendments in CGST Act, UTGST Act, and the corresponding SGST Acts in view of creation of UTs of Jammu & Kashmir and Ladakh.

Need any assistance than 


Wednesday, 1 May 2019

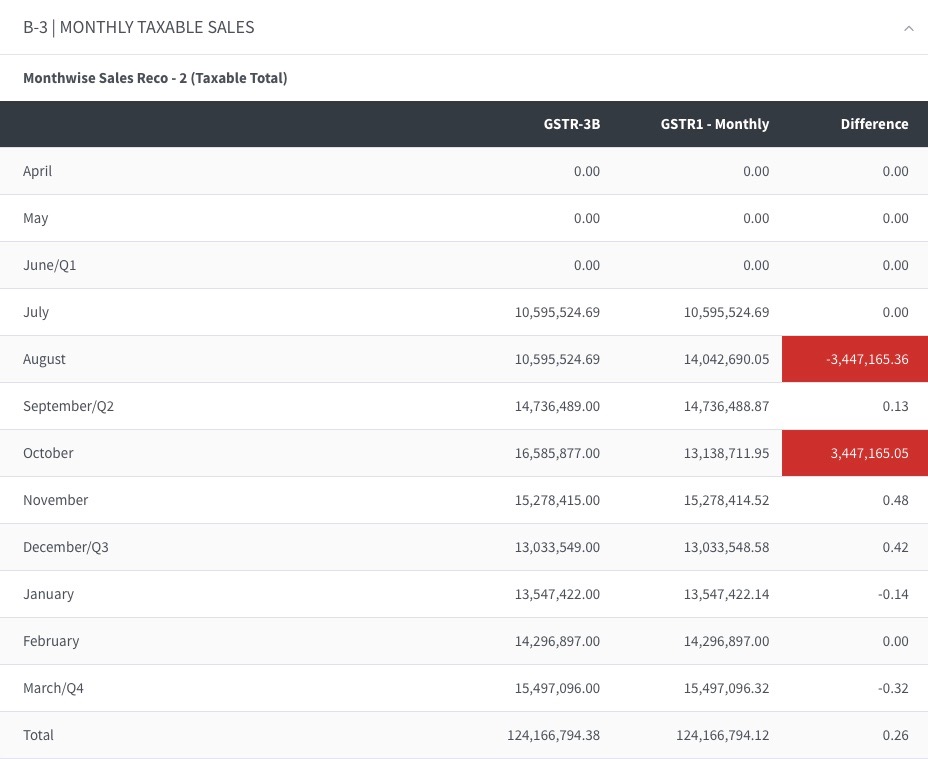
GST AUDIT – How to Reconcile GSTR 3B and GSTR 1

How to map GSTR 1 vs GSTR 3B
GSTR-1, filed by the supplier, contains invoice-wise and category-wise details of all outward supplies made in a year
GSTR-3B is the summary return based on which tax is deposited by the supplier. It contains category-wise summary of both inward and outward supplies and tax payment details.
Now, the reconciliation of GSTR-3B and GSTR-1 is of utmost importance since GSTR-3B is a manual return, i.e. it is not auto populated on the basis of GSTR-1 and GSTR-2A. There might be instances where supplier has shown an invoice in GSTR-1 but has not paid tax on that invoice in GSTR-3B. GST department uses data analytics to reconcile GSTR-1 and GSTR-3B filed by a supplier. That means it automatically reconciles GSTR-1 with GSTR-3B and issues a GST notice for mismatches.
One of the main reason of the difference is, wrong calculation of revenue & tax liability at the time of filling GSTR-3B For a large business organisation, it is very common to have difference in Actual turnover & the turnover recorded in books. This may result in GST liability if turnover as recorded in books of accounts is less than the actual turnover. Again this may result in late payment of GST, which may lead to applicability of interest. Nominal difference in is still accepted, but large data gaps is matter of concern because this can result in heavy interest liability
Here is a format for reconciliation 


Need any assistance than 

Tuesday, 15 January 2019

GST on advance payments

Generally, GST is imposed on a supplier of goods and service at the time of receipt of payment. However, in some cases, an advance payment is first made by the recipient of the goods or/and service or both to the supplier. In this article, we will discuss the applicability of GST on advance payments.

GST on Advance Payment

When a payment is made ahead of its actual schedule such payment is termed as advance payment, such as making the payment for the goods or service before the receipt of goods or service. In addition to this, sometimes the supplier of the goods and service requires an advance payment as a safeguard against non-payment, or to cover its costs for supplying a product or rendering of a service.
For example, the rent of a banquet hall is Rupees 1,00,000 for a single day accommodation. To ensure that the booking gets confirm we have to make an upfront payment of Rupees 15,000 to the owner. This upfront payment is called an advance payment.
As mentioned above, GST is to be paid at the time of delivery of the goods or completion of services. However, an exception to this rule is the receipt of advances. Therefore, If a supplier demands an advance payment before delivering/rendering the goods or services as the case may be, GST has to be paid on the advance amount even if the goods have not been delivered or service has not yet been rendered.

GST Advance Receipt Voucher

The advance receipt voucher is required to contain the following details in order to comply with the GST rules:
  • Name, address and GST Identification number of the supplier of the goods or/and service;
  • The advance receipt voucher must contain a consecutive serial number not exceeding sixteen characters, containing alphabets or numerals or special characters;
  • Date of issue;
  • Name, address and GST Identification Number, if registered, of the recipient;
  • Details of the of goods or services;
  • Amount of advance received;
  • The rate of tax;
  • Amount of tax charged in regard to taxable goods or services;
  • Place of supply along with the name of State and its code
  • Whether the GST is payable under the reverse charge basis; and
  • Signature or digital signature of the supplier or his authorised representative.

Treatment of Advance Received In GST Return

Details of the amount received as the advance are required to be mentioned in sr. no. 11A of the GSTR – 1 return. As it shows the figure of the advance money received in the tax period for which invoice has not been issued.
Additionally, it is important to note that in sr. no. 11A of the GSTR – 1 return figures of the advance money received must be bifurcated in two parts i.e. advance money received against intra-state supplies and advance money received against inter-state supplies. However, consolidated figures of the advance money received are to be stated in the same, details of each advance money received need not to be mentioned.
The gross amount of advance money received is required to be mentioned under the head ‘Gross Advance Received / Adjusted’ and matching tax liability is required to be reflected under ‘Central’ and ‘State/ UT’ head in case of intra-state supplies and under ‘integrated’ head in case of inter-state supplies.

Need any assistance than 

Anti-profiteering

Anti-profiteering Today we are discussed about the most important topic that is the benefit of Gst will be transferred to the ultimat...